Insurance products
Insurance options for your business
Every business operates differently. Your industry, equipment, premises and day-to-day activities all influence the insurance you may need. EIB Melbourne helps you explore available options, understand important policy details and arrange cover suited to your circumstances.
Explore our key service areas below, then contact us to discuss your business. The examples are not a standard package: cover is subject to insurer acceptance and the selected policy's terms, conditions, limits, excesses and exclusions.
01 / Business
Business Insurance
Your business relies on more than its premises. Equipment, stock, customer relationships and the ability to keep trading all contribute to its operation. An insurance review helps you consider these different exposures together.
EIB Melbourne can help you explore business insurance options and understand the details behind a quote, including the limits, excesses and exclusions that may affect how a policy responds. Whether you are establishing a business, reviewing your renewal or changing your operations, we start by understanding what you do.
Depending on your needs and insurer availability, areas to discuss may include:
- Business premises, contents and stock.
- Public and products liability.
- Theft, glass and machinery breakdown.
- Business interruption.
- Professional indemnity and management liability.
- Commercial motor insurance.
- Cyber insurance, including data breach and cyber incident considerations.
Some covers, including cyber insurance, may require separate policies. Cyber cover is subject to the insured events, security requirements, limits and exclusions in the selected policy. Business interruption does not cover every reduction in income; it depends on specified policy triggers and the cover selected.

02 / Trades
Trades Insurance
Working across different sites can expose your trade business to a range of risks. The tools you carry, the services you provide and the responsibilities you accept under contracts can all influence your insurance requirements.
EIB Melbourne helps trades and contracting businesses explore cover options for their activities, equipment and work vehicles. Tell us about the work you perform, where you operate and whether you use subcontractors so we can discuss the relevant insurance considerations.
Areas to discuss may include:
- Public and products liability.
- Tools and portable equipment.
- Commercial utes, vans and other work vehicles.
- Equipment storage and transport.
- Insurance requirements specified in client contracts.
Tools are not automatically covered wherever they are kept. Theft conditions, security requirements, item limits and exclusions can affect a policy's response. A policy also may not cover every liability accepted under a contract.

03 / Hospitality
Hospitality Insurance
Hospitality businesses depend on reliable equipment, suitable premises and the ability to welcome customers. An incident affecting any of these can interrupt day-to-day operations.
EIB Melbourne can help cafes, restaurants, hotels and accommodation businesses explore insurance options that reflect how they operate. We discuss your activities, property and equipment, along with changes such as renovations, delivery services or additional events.
Areas to discuss may include:
- Premises, contents and stock.
- Public and products liability.
- Theft and glass.
- Machinery and equipment breakdown.
- Refrigerated stock deterioration.
- Business interruption.
These covers are not automatically included together. Equipment breakdown and stock deterioration may require different cover, while business interruption depends on the policy's specified triggers, limits and conditions.

04 / Transport
Transport Insurance
Transport insurance considerations extend beyond the vehicle itself. What you carry, where you travel and the responsibilities you accept can influence the cover your business needs.
EIB Melbourne assists owner operators and businesses with commercial fleets to explore available insurance options. We can discuss your vehicles, drivers, routes, cargo and storage arrangements, along with relevant insurance requirements in your contracts.
Areas to discuss may include:
- Commercial motor and fleet insurance.
- Public liability.
- Marine cargo or goods-in-transit requirements.
- Depot property and business assets.
- Insurance considerations associated with transport contracts.
Cover for damage to a vehicle does not necessarily cover the goods being carried or your liability for those goods. These exposures should be discussed separately, with reference to the relevant policy terms.
05 / Construction
Construction Insurance
Construction projects bring together people, materials, equipment and changing site conditions. The work you undertake and the responsibilities set out in your contracts shape the insurance considerations for each project.
EIB Melbourne can help builders and construction businesses explore insurance options for their operations and projects. We discuss the type and value of your work, the sites you operate on and your use of subcontractors.
Depending on your activities and insurer acceptance, options to discuss may include:
- Contract works and materials.
- Public and products liability.
- Plant, machinery and portable equipment.
- Commercial vehicles.
- Insurance requirements in building contracts.
Contract works cover is not a substitute for every insurance requirement in a building contract. Existing structures, defects and liabilities assumed under contract may be excluded or limited. Confirm the scope, insured parties and policy conditions for each project.
06 / IT
Information Technology (IT) Insurance
IT businesses support the systems, software and services that their clients rely on. Service errors, equipment damage and cyber incidents can create different exposures for your business.
EIB Melbourne can help technology consultants, software businesses and IT service providers discuss insurance options. We consider the services you provide, the information you handle and the obligations included in your client agreements.
Depending on your activities and insurer acceptance, options to discuss may include:
- Professional indemnity.
- Public and products liability.
- Cyber insurance.
- Computers and business equipment.
- Business interruption and contractual insurance requirements.
Professional indemnity and cyber insurance respond to different events and may require separate policies. Contractual liability, prior incidents and the timing of a claim can affect cover. Security requirements, exclusions, limits and excesses should be reviewed.
07 / Media
Media Insurance
Media and creative businesses work across changing briefs, locations and production schedules. Your equipment, published work and professional services can each bring different insurance considerations.
EIB Melbourne can assist production businesses, photographers, agencies and other media professionals to explore available options. We discuss your activities, equipment, use of freelancers and the requirements of your clients.
Depending on your activities and insurer acceptance, options to discuss may include:
- Professional indemnity and media liability considerations.
- Public liability.
- Cameras, production and portable equipment.
- Equipment used on location or in transit.
- Cyber insurance and business interruption.
Cover for defamation, intellectual property claims, hired equipment and overseas work varies by policy and is not automatic. Your activities, publication channels and locations need to be declared and considered when arranging cover.
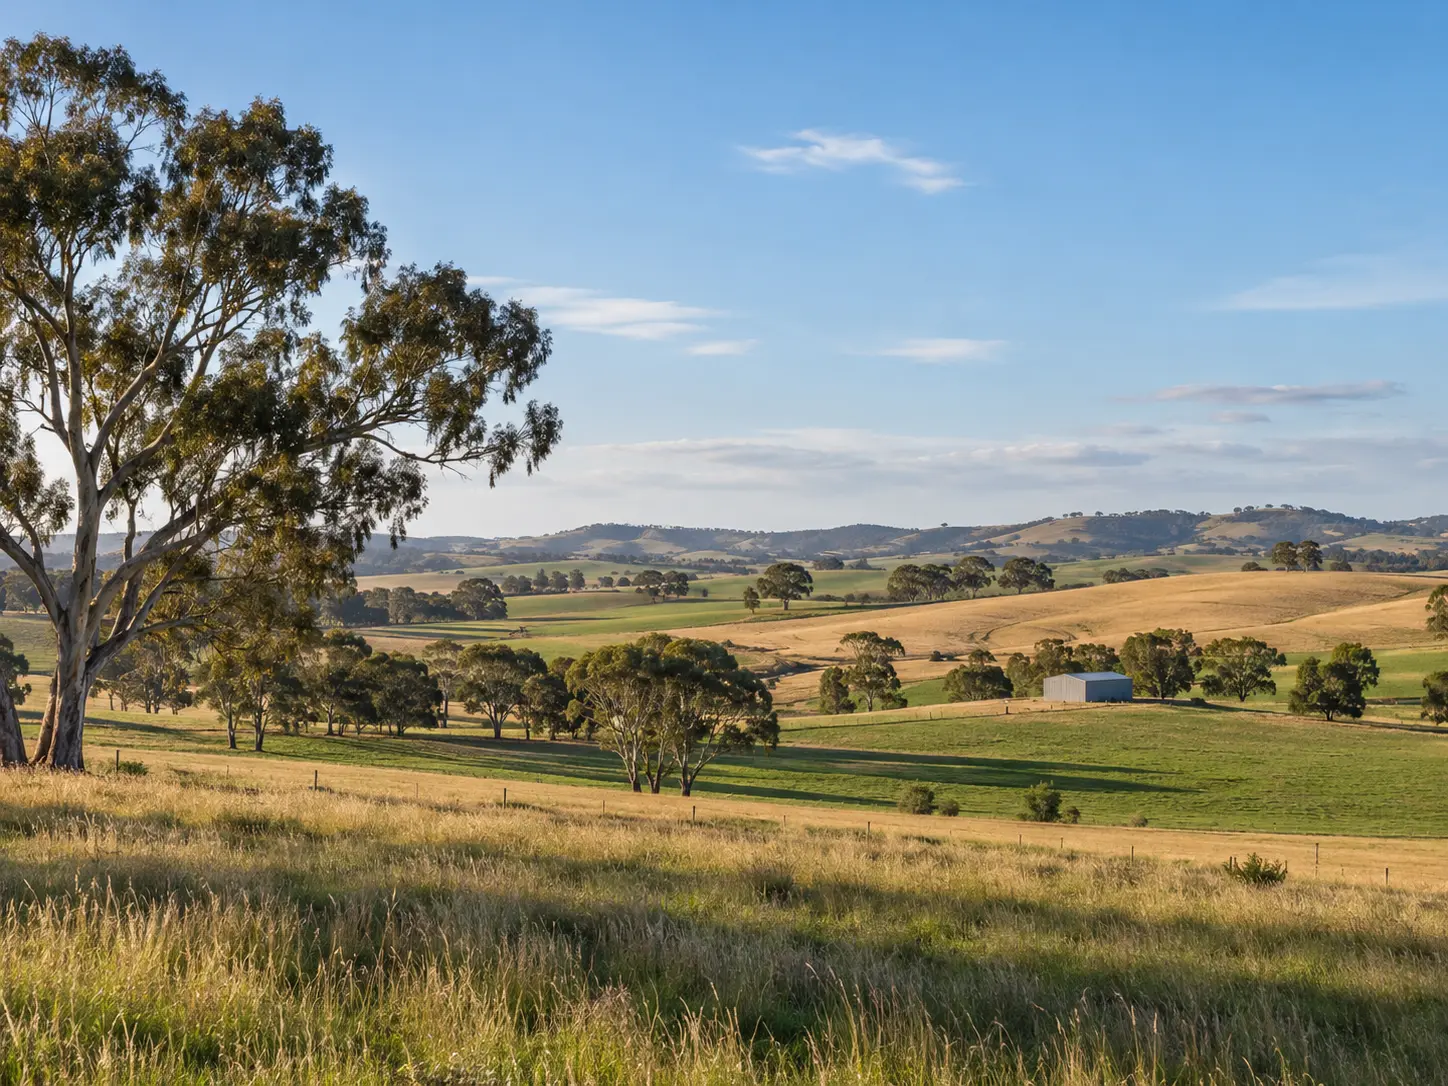
08 / Rural
Rural Insurance
Rural businesses depend on property, machinery and the ability to operate through changing seasons. The activities carried out on your land influence the insurance options worth considering.
EIB Melbourne can help rural and farming businesses discuss their property, equipment and liability exposures. Tell us about your operations, vehicles, storage and any additional activities such as contracting or farm stays.
Depending on your activities and insurer acceptance, options to discuss may include:
- Farm buildings, contents and equipment.
- Farm machinery and commercial vehicles.
- Public and products liability.
- Theft and accidental damage, where included.
- Business interruption following events insured by the selected policy.
Flood, bushfire, livestock and crop exposures need specific discussion. Cover and availability vary by insurer, and some risks may be excluded or require specialist insurance. A rural policy does not automatically cover every weather event or loss of income.
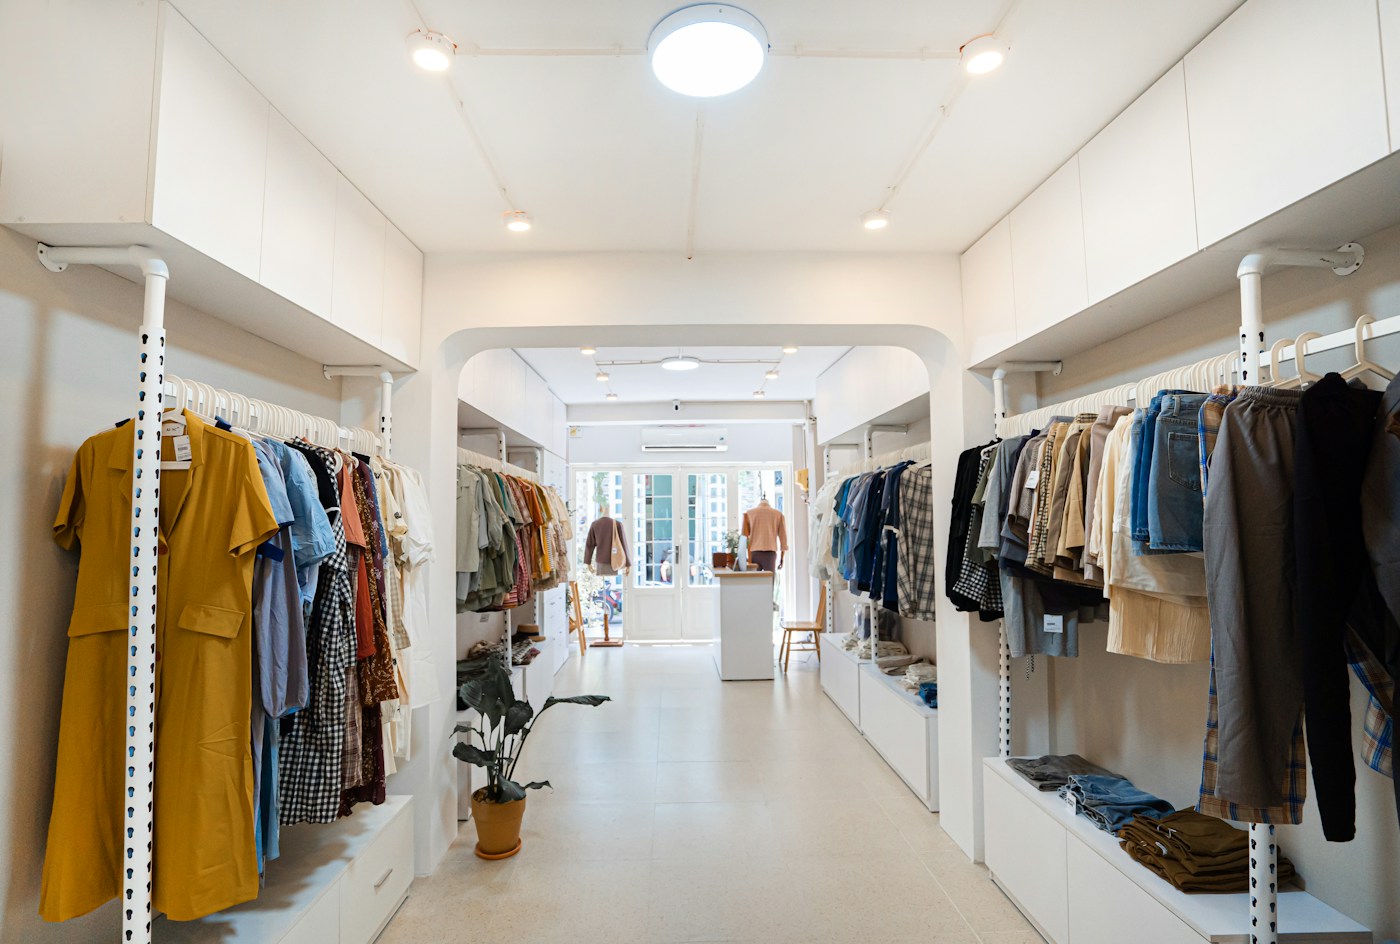
09 / Retail
Retail Insurance
Retail businesses rely on their stock, premises and customer experience. Whether you trade from a shopfront, online or both, an interruption can affect several parts of your business.
EIB Melbourne can help retailers explore insurance options that reflect how and where they trade. We discuss your products, stock values, storage arrangements, customer interactions and online sales activities.
Depending on your activities and insurer acceptance, options to discuss may include:
- Premises, contents and stock.
- Public and products liability.
- Theft, glass and money.
- Business interruption.
- Cyber insurance and goods in transit.
Off-site stock, goods in transit and cyber incidents may require specific or separate cover. Business interruption is subject to insured events, waiting periods where applicable, indemnity periods and other policy conditions; it does not cover every downturn in sales.
Let's talk
Let's talk about your insurance needs
Starting a business, reviewing your cover or making changes to your operations? Contact EIB Melbourne to discuss your circumstances and the next steps.
Phone: 1300 003 553
Email: admin@eibmelb.com.au
This information is general and does not take into account your objectives, financial situation or needs. Consider its appropriateness for your circumstances. The covers described are examples for discussion and are not automatically included in every policy. Availability is subject to insurer acceptance. Cover depends on the selected policy's terms, conditions, limits, excesses and exclusions. Read the relevant Product Disclosure Statement, where applicable, and policy wording before making a decision.